What Does the IRS Say About Staking Rewards?
The IRS settled this question, at least officially, in Revenue Ruling 2023-14. Staking rewards are ordinary income in the year you receive them. The amount of income is the fair market value of the tokens at the time of receipt.
This mirrors the treatment of mining rewards established in IRS Notice 2014-21. The IRS has consistently treated newly created crypto, whether mined or staked, as income at receipt, not at sale.
What About the Jarrett Case?
You may have heard about Joshua Jarrett, who argued that staking rewards are newly created property, not income, and therefore not taxable until sold. The IRS initially issued a refund to settle the case, then tried to reclaim it. The Sixth Circuit ultimately ruled against the IRS’s attempt to force the refund back.
Here’s the practical reality: the IRS issued Rev. Rul. 2023-14 after this litigation specifically to clarify its position. The ruling applies to federal tax treatment across the United States regardless of the Jarrett outcome. Unless you are prepared to litigate your own case in federal court, staking rewards are taxable income at receipt.
Audit risk of not reporting staking income: High. The IRS receives 1099-MISC from Coinbase and other exchanges for rewards above $600.
How Staking Income Is Calculated
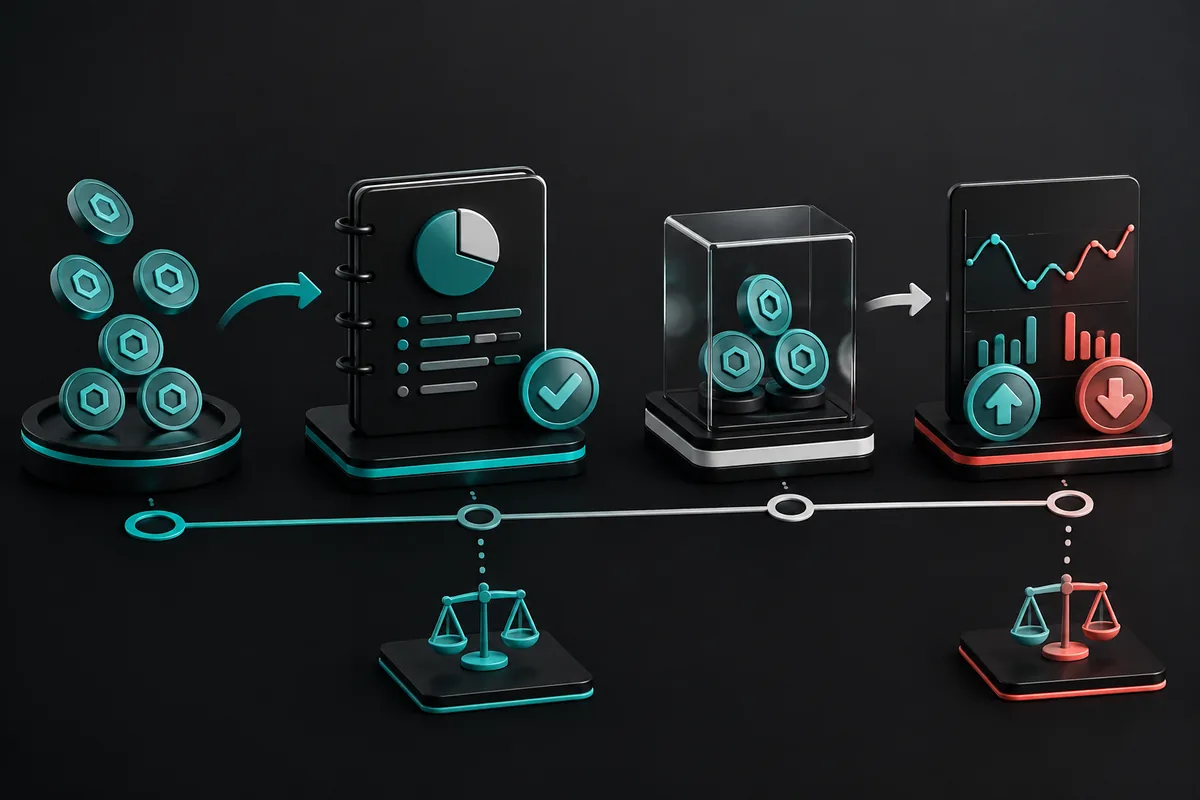
Your taxable income from staking equals: quantity of tokens received × fair market value per token at time of receipt.
This creates a cost basis in those tokens equal to the income you recognized. When you later sell, swap, or spend them, you calculate capital gain or loss using that cost basis, the difference between what you reported as income and what you sold for.
Staking Rewards: Ordinary Income vs. Capital Gains
| Event | Tax Treatment | Rate |
|---|---|---|
| Receiving staking rewards | Ordinary income | Your marginal rate |
| Selling staking rewards (held < 1 year) | Short-term capital gain | Your marginal rate |
| Selling staking rewards (held > 1 year) | Long-term capital gain | 0%, 15%, or 20% |
What About Liquid Staking (stETH, cbETH, etc.)?
Liquid staking tokens add another layer. When you stake ETH and receive stETH, two questions arise: (1) is the receipt of stETH a taxable exchange of ETH? (2) are the rebase rewards that accrue to stETH taxable income?
The IRS has not issued specific guidance on liquid staking tokens as of mid-2025. Most practitioners treat the initial exchange of ETH for stETH as a taxable disposition and the rebases as ordinary income at receipt, consistent with Rev. Rul. 2023-14. This is the conservative, audit-safe approach.
DeFi Yield: Same Rules, More Complexity
Yield farming, liquidity mining, and DeFi lending rewards follow the same framework as staking: income at receipt, at fair market value. The complications are practical:
- Rewards may accrue continuously, requiring you to track FMV at each distribution
- Some protocols pay in new tokens that have no liquid market at issuance, creating valuation questions
- Providing liquidity to AMMs (Uniswap, Curve, etc.) may trigger a taxable exchange when you deposit or withdraw
- Impermanent loss is generally not a deductible loss until you actually withdraw from the pool
How to Track Staking and DeFi Income
Most crypto tax software can handle staking rewards if your data is complete. The problem is completeness. Exchanges often don’t export reward history accurately, on-chain rewards from DeFi protocols require manual import or API integration, and some rewards appear as token transfers rather than clearly labeled income events.
We work with Koinly, CoinTracker, CoinLedger, ZenLedger, Awaken Tax, and Summ. If you have multi-protocol DeFi activity, we can identify what your software is missing and reconcile the gaps.
Official guidance and a practical next step
Primary source: IRS Revenue Ruling 2023-14.
Koinly can help organize staking transactions, but you still need complete wallet history, timestamps, fair-market-value support, and a review of when you obtained dominion and control. View Koinly.
Affiliate disclosure: Bugaboo Bookkeeping may earn a commission if you sign up through this link, at no additional cost to you. The relationship does not change our evaluation of the tool.
See our nationwide crypto tax reconciliation services and free crypto tax prep checklist.
Common questions
Are staking rewards taxable when they are received?
For the cash-method taxpayer addressed in Revenue Ruling 2023-14, rewards are included in gross income when the taxpayer gains dominion and control over the rewarded units.
What basis do staking reward units receive?
The amount included in income generally becomes the tax basis of the rewarded units. Keep the fair-market-value calculation and timestamp with the lot record.
What happens when staking rewards are sold later?
A later sale or exchange is a separate disposition. The difference between amount realized and adjusted basis produces a gain or loss, subject to the applicable holding period and character rules.