The Core Tax Question: When Is a Loss Actually a Loss?
For FTX, Celsius, BlockFi, Voyager, and similar bankruptcies, the threshold question is: when do you get to recognize the loss? There is no single tax rule for every crypto exchange bankruptcy. The Taxpayer Advocate Service has published guidance for some individual investment losses, while the applicable result still depends on the customer’s asset or claim rights, the plan, recoveries, and the tax theory supported by the facts. Existing rules for sales or exchanges, bad debts, and theft or other losses may lead to different outcomes.
The answer depends on which theory applies to your situation, and that depends on what you had on the platform (securities vs. loans vs. custody assets) and when you’re filing.
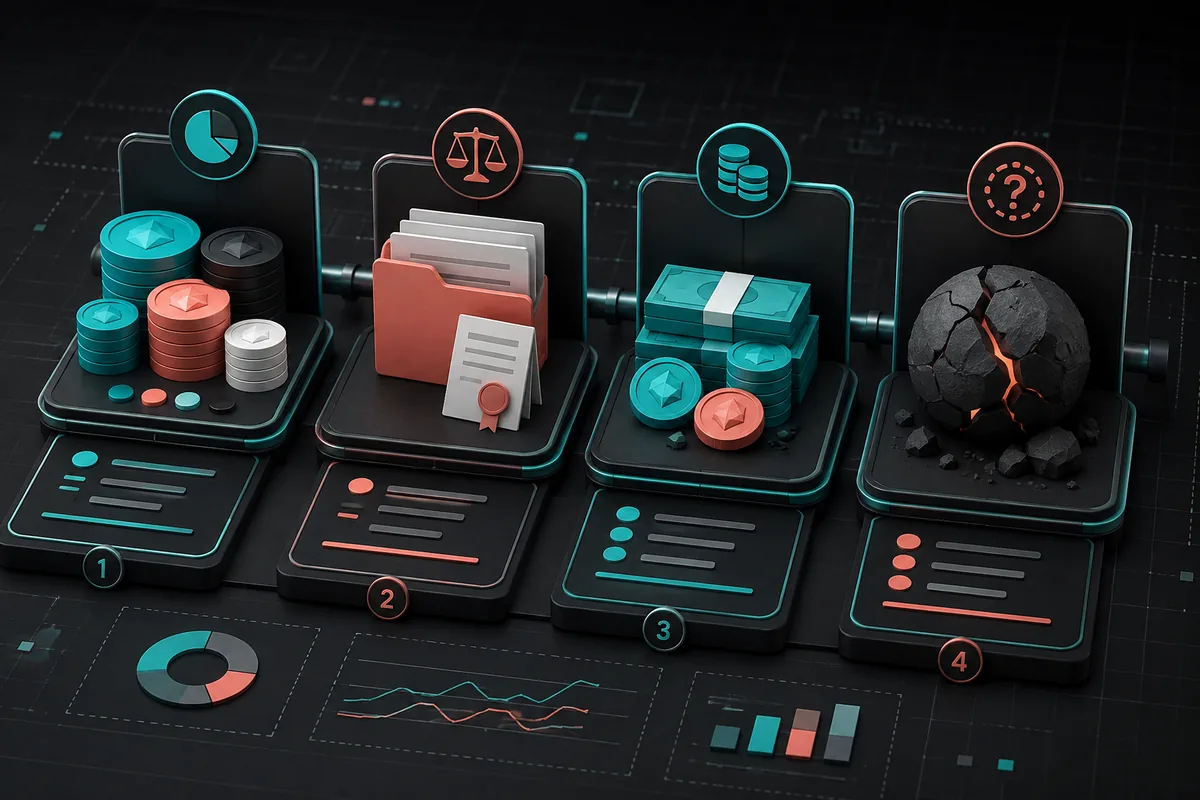
Four Legal Theories, Four Different Results
Theory 1: Worthless Securities (IRC § 165(g))
Section 165(g)(2) uses a narrow definition of security: corporate stock or stock rights, or certain bonds, debentures, notes, and certificates of indebtedness issued in registered form or with interest coupons. A digital asset does not qualify merely because it was held in an exchange account. A lending or bankruptcy claim may require a separate debt analysis, and a section 165(g) deduction requires the qualifying security to become completely worthless in the year claimed.
Theory 2: Personal Theft Loss (IRC § 165(c)(3))
Section 165(h)(5) permanently limits most personal casualty and theft losses, as amended by the One Big Beautiful Bill Act in July 2025. Beginning in 2026, the exception covers qualifying federally declared and state-declared disasters, along with the limited rule for personal casualty gains. That personal-loss rule is different from a theft loss incurred in a transaction entered into for profit under section 165(c)(2).
Fraud or a criminal conviction does not automatically make an exchange bankruptcy eligible for the Ponzi scheme safe harbor. Revenue Ruling 2009-9 and Revenue Procedure 2009-20 require specific facts, including a qualifying fraudulent investment arrangement and the required discovery-year events. The taxpayer also must address basis and any reasonable prospect of recovery.
Audit risk: Medium-high. The legal theory, applicable state theft law, basis, discovery year, and expected bankruptcy recoveries all need support.
Theory 3: Bad Debt (IRC § 166)
If the customer’s legal relationship with the platform created a bona fide debt, a wholly worthless nonbusiness bad debt may be treated as a short-term capital loss. The account agreement, bankruptcy claim, and recovery rights matter. An exchange deposit should not be labeled a loan without reviewing those documents.
Theory 4: Profit-Motivated Theft Loss (IRC § 165(c)(2))
Section 165(c)(2) is the live theft-loss route when an individual entered the transaction primarily for profit. IRS Chief Counsel Advice 202511015 explains that an investment transaction can satisfy the profit-motive requirement and that a theft loss is generally not sustained while a reasonable prospect of recovery remains. The memorandum addresses scam losses, not FTX or Celsius, and Chief Counsel Advice is not precedent, so it does not decide the treatment of an exchange-bankruptcy claim.
For an exchange failure, the taxpayer still must establish a theft under the law of the applicable state, connect the loss to the profit-motivated transaction, document adjusted basis, and determine when recovery became no longer reasonably possible. An open bankruptcy claim or expected distribution can delay or reduce a deductible loss.
What About Bankruptcy Distributions?
Record each cash or digital-asset distribution, its date and value, the claim it satisfied, and whether any rights remain. A distribution is not automatically a sale with proceeds equal to its value. Its tax treatment depends on the account agreement, the bankruptcy plan, the property or claim surrendered, the assets received, prior deductions, and any remaining recovery rights.
For an individual who held digital assets as investments, the Taxpayer Advocate Service explains that a settlement received in exchange for the digital assets can be treated as a sale. That illustration does not decide an in-kind partial distribution or every creditor claim. Do not calculate a capital loss by simply subtracting one payment from the original asset cost without first identifying what was exchanged and what basis remains.
If a prior-year loss deduction was properly claimed, a later recovery may have a tax effect under the tax-benefit rule. The amount and character require review of the earlier return and the recovery documents. Do not assume that every distribution is income or that every payment creates an immediate capital loss.
Track the Events Year by Year
- Withdrawal freeze: Preserve the account and asset records. A freeze alone does not establish a deductible loss.
- Bankruptcy filing and claim: Save the agreement, proof of claim, court notices, and expected-recovery information. Determine whether a loss is fixed under a supported legal theory before claiming one.
- Each distribution: Record exactly what arrived and which claim rights were reduced or extinguished. Review the tax treatment before coding a sale, income item, or return of basis.
- Final resolution: Reconcile all recoveries and any remaining claim or asset basis. Have the year, amount, and character reviewed against the final plan and prior returns.
Documentation: What the IRS Will Want to See
If you’re claiming any kind of loss related to a crypto exchange failure, document:
- Account statements showing your balance at the time of freeze/bankruptcy
- Cost basis records for the assets (purchase dates, prices paid)
- Your claim filed with the bankruptcy court (if applicable)
- Any distributions received and their reported value
- The legal theory your CPA used and why it applies to your situation
This documentation needs to survive an IRS examination. “I lost money on FTX” is not a defensible tax position. The theory, the calculation, and the records all matter.
In Crypto Tax Software: Preserve the Claim Trail
Do not mark frozen assets as “lost” or “stolen” merely because withdrawals stopped. Do not import a distribution as a new zero-history acquisition without preserving the original basis and claim records. Keep the frozen holdings, claim, each recovery, and any unresolved amount in a separate workpaper. Enter final tax treatment in software only after the applicable transaction and loss theory are supported. Compare the software result with the filed-return workpaper.
Sources reviewed
This article was reviewed against current primary guidance on September 17, 2026. Loss treatment remains fact-specific, and later recoveries can change the result.
- 26 U.S.C. § 165: Losses
- Public Law 119-21, section 70109: Limitation on casualty loss deduction
- IRS Chief Counsel Advice 202511015: Theft losses and transactions entered into for profit
- IRS Publication 547: Casualties, Disasters, and Thefts
- IRS Publication 550: Investment Income and Expenses
- Revenue Ruling 2009-9: Theft loss from a fraudulent investment arrangement
- Revenue Procedure 2009-20: Optional safe harbor for qualifying fraudulent arrangements
A practical next step
Affiliate disclosure: Bugaboo Bookkeeping may earn a commission if you sign up through this link, at no additional cost to you. The relationship does not change our evaluation of the tool.
Crypto tax software can help organize transactions and recoveries, but it cannot decide the legal character or timing of a bankruptcy loss without the claim documents and final facts. View Koinly.
See our nationwide crypto tax reconciliation services and free crypto transaction log.
Common questions
Is a frozen crypto exchange balance an automatic tax loss?
No. Loss treatment depends on the taxpayer’s property rights, the bankruptcy claim, recoveries, and the event that finally establishes the loss or disposition.
How should I track bankruptcy recoveries?
Preserve the original asset basis, claim records, court notices, and each cash or token recovery. Keep unresolved amounts separate until the tax treatment is supportable.
Can a tax form replace the bankruptcy records?
No. Any tax form should be reconciled to the transaction ledger, basis records, claim documents, and actual recoveries.