BUGABOO INSIGHTS
Are Staking Rewards Taxable? What Rev. Rul. 2023-14 Says
On this page
- What Does the IRS Say About Staking Rewards?
- What About the Jarrett Case?
- How Staking Income Is Calculated
- Staking Rewards: Income and a Later Sale
- What About Liquid Staking (stETH, cbETH, etc.)?
- DeFi Yield Needs Its Own Review
- How to Track Staking and DeFi Income
- Official guidance and a practical next step
- Common questions
- More from the Blog
Revenue Ruling 2023-14 states the IRS position for the cash-method taxpayer and proof-of-stake validation rewards it describes: include fair market value in income when dominion and control begins. Liquid-staking and other DeFi arrangements need their own review.
What Does the IRS Say About Staking Rewards?
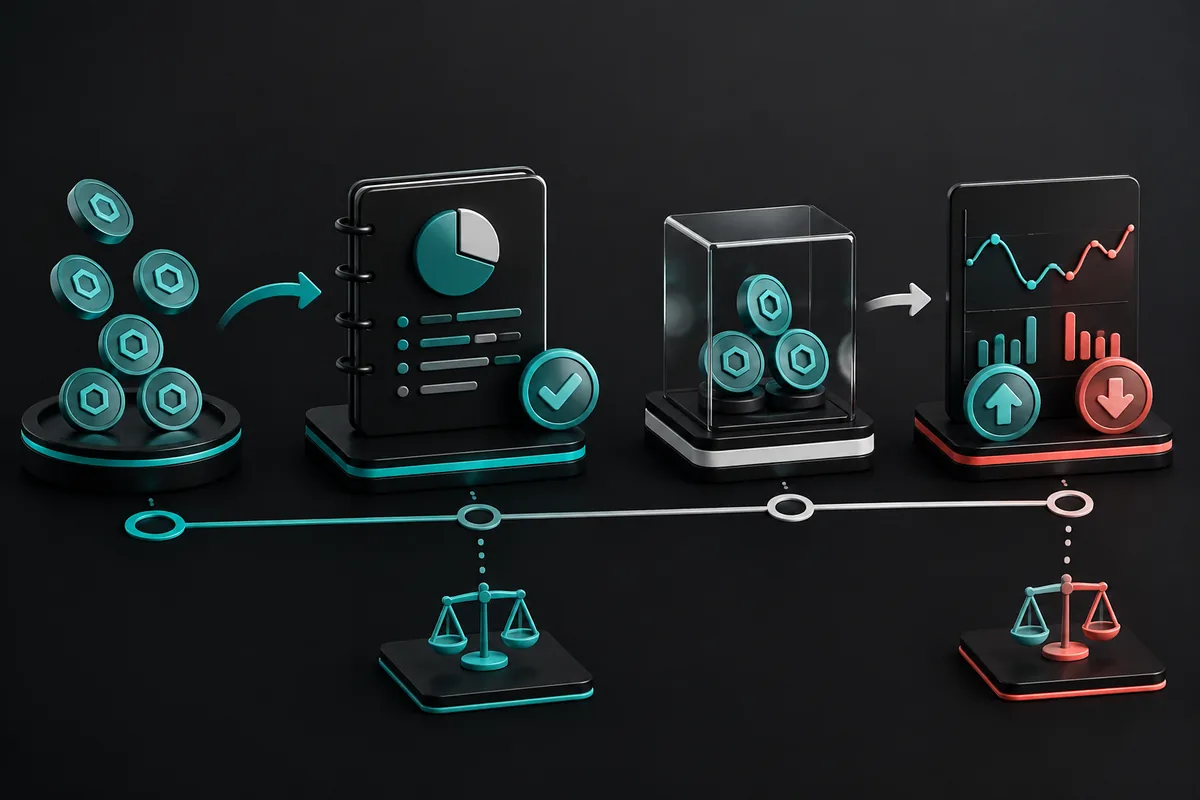
Revenue Ruling 2023-14 addresses a cash-method taxpayer who receives additional proof-of-stake validation rewards. The fair market value is included in gross income when the taxpayer gains dominion and control over the new units. The ruling does not resolve every liquid-staking or DeFi arrangement.
IRS Notice 2014-21 addresses mining income. Keep a separate record of the units, valuation, and date of control for any reward, then analyze a later disposition separately.
What About the Jarrett Case?
Jarrett involved a refund for one taxpayer’s 2019 return. The Sixth Circuit held that the IRS’s payment of the full refund made that refund lawsuit moot. The court did not decide that staking rewards are tax-free or establish a rule for other taxpayers. Read the court’s opinion.
Revenue Ruling 2023-14 states the IRS position for a cash-method taxpayer who receives additional proof-of-stake validation rewards: include fair market value when the taxpayer gains dominion and control. Its facts do not resolve every liquid-staking, receipt-token, or DeFi arrangement.
How Staking Income Is Calculated
For rewards covered by the ruling, gross income generally equals: quantity of reward tokens × fair market value per token when dominion and control begins.
The amount included in income generally becomes the basis of those reward units. For a later sale, swap, or spending transaction involving units held as capital assets, calculate gain or loss as amount realized minus adjusted basis. Keep any applicable transaction-cost adjustments with the lot records. The IRS capital gains guidance explains the holding-period rules.
Staking Rewards: Income and a Later Sale
The sale examples below assume the rewarded units are held as capital assets. Business or other facts can change character, and additional taxes may apply.
| Event | Tax Treatment | Rate |
|---|---|---|
| Receiving staking rewards | Ordinary income | Your marginal rate |
| Selling staking rewards (held one year or less) | Short-term capital gain | Your marginal rate |
| Selling staking rewards (held > 1 year) | Long-term capital gain | 0%, 15%, or 20% |
What About Liquid Staking (stETH, cbETH, etc.)?
Liquid-staking arrangements require a separate review. Receiving a receipt token, exchanging it, and receiving a rebase or other reward can involve different rights and events. Revenue Ruling 2023-14 addresses additional validation-reward units received by a cash-method taxpayer, not every receipt-token exchange or rebase. Do not assume that the initial ETH-to-token transaction is always taxable, or that every displayed rebase amount is income at the moment it appears. Document the protocol terms, the assets and rights exchanged, and when any new units became available. Have a qualified tax professional review the resulting treatment.
DeFi Yield Needs Its Own Review
Yield farming, liquidity incentives, and lending returns may create income or a property disposition, but the staking ruling does not decide every arrangement. Review what you transferred, what rights you received, whether you received new property, and when you gained control. A liquidity-pool deposit or withdrawal may require an exchange analysis. An app’s “impermanent loss” display is not, by itself, a tax deduction.
How to Track Staking and DeFi Income
Most crypto tax software can handle staking rewards if your data is complete. The problem is completeness. Exchanges often don’t export reward history accurately, on-chain rewards from DeFi protocols require manual import or API integration, and some rewards appear as token transfers rather than clearly labeled income events.
We work with Koinly, CoinTracker, CoinLedger, ZenLedger, Awaken Tax, and Summ. If you have multi-protocol DeFi activity, we can identify what your software is missing and reconcile the gaps.
Official guidance and a practical next step
Primary source: IRS Revenue Ruling 2023-14.
Affiliate disclosure: Bugaboo Bookkeeping may earn a commission if you sign up through this link, at no additional cost to you. The relationship does not change our evaluation of the tool.
Koinly can help organize staking transactions, but you still need complete wallet history, timestamps, fair-market-value support, and a review of when you obtained dominion and control. View Koinly.
See our nationwide crypto tax reconciliation services and free crypto tax prep checklist.
Common questions
Are staking rewards taxable when they are received?
For the cash-method taxpayer addressed in Revenue Ruling 2023-14, rewards are included in gross income when the taxpayer gains dominion and control over the rewarded units.
What basis do staking reward units receive?
The amount included in income generally becomes the tax basis of the rewarded units. Keep the fair-market-value calculation and timestamp with the lot record.
What happens when staking rewards are sold later?
A later sale or exchange is a separate disposition. The difference between amount realized and adjusted basis produces a gain or loss, subject to the applicable holding period and character rules.
Need help organizing staking records?
Start with a free consultation to discuss your wallet history and staking records. If a deeper written review is useful, we may recommend an optional $500 Crypto Tax Diagnostic afterward. Tax treatment of liquid staking and other uncertain events needs review by a qualified tax professional.
Book My Free ConsultationMore from the Blog
FIFO, HIFO, or Spec ID: Which Method Saves You the Most?
Your cost basis method determines how much tax you owe on every crypto sale.
FTX and Celsius Bankruptcy: How to Handle the Tax Treatment
Bankruptcy distributions, frozen assets, and how to document losses correctly.
How to Know If Your Books Are Actually Reconciled
There’s a big difference between entered and reconciled.