Crypto tax records
Crypto Cost Basis Methods: FIFO, HIFO, and Specific Identification
FIFO is the fallback when you cannot adequately identify the digital-asset units sold. HIFO is not a separate IRS method. It is a specific-identification strategy that works only when your records and broker instructions support the selected lots.
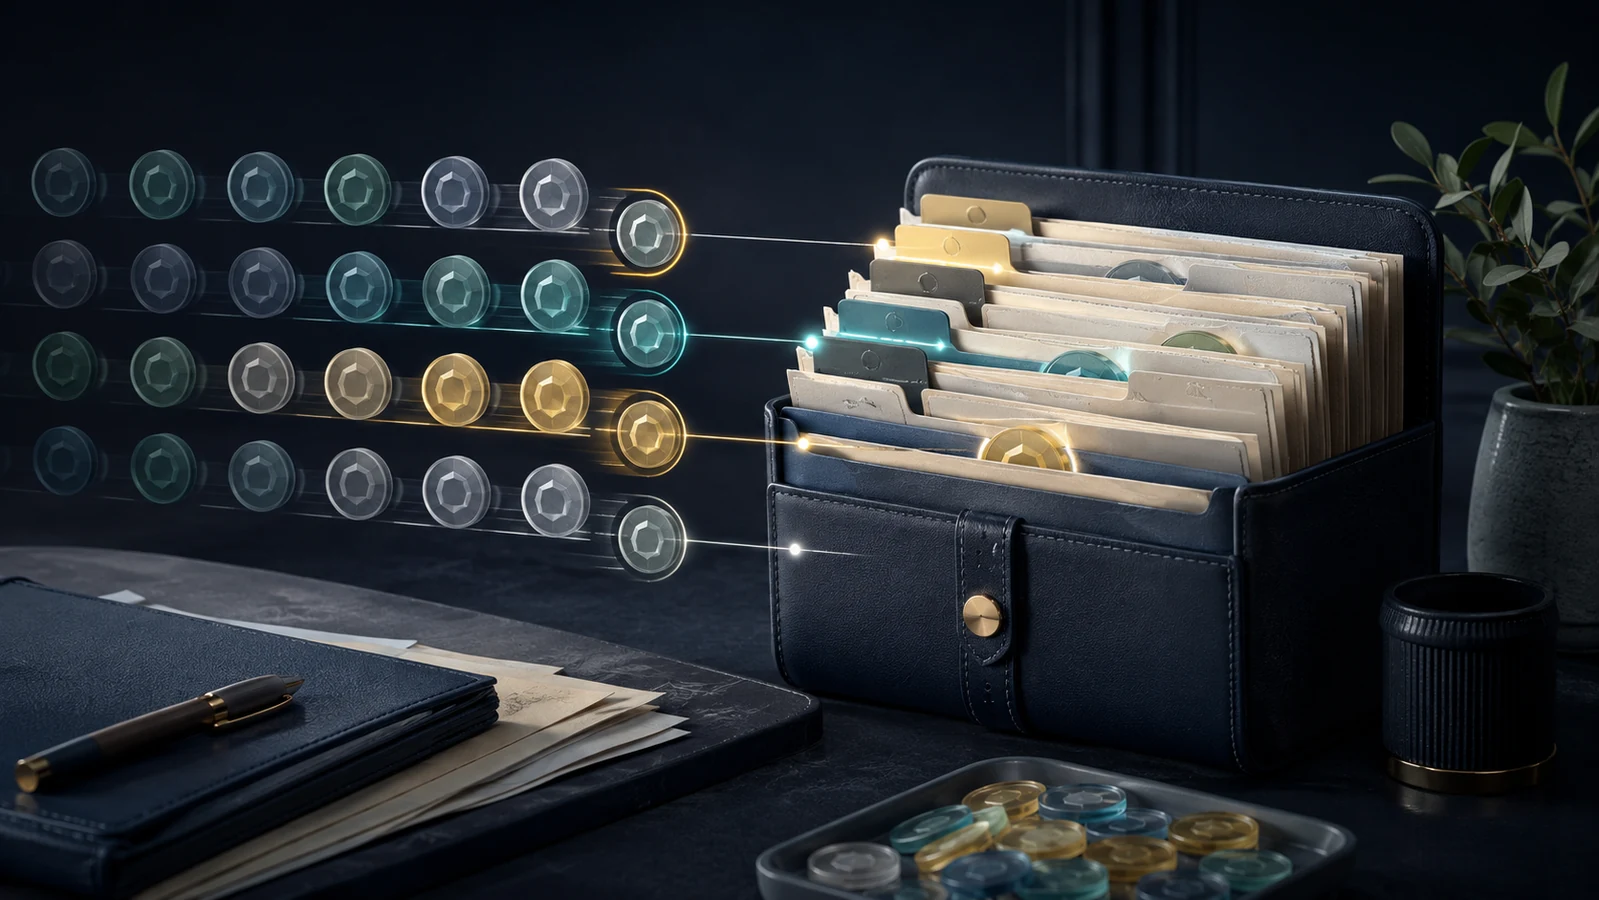
A cost-basis method answers one question: Which acquisition lot did you dispose of? The answer affects basis, holding period, and gain or loss. It does not change what you actually received from the sale.
If you bought the same token at several prices, a sale must be matched to one or more acquisition lots. That match is easy to overlook because tax software can produce a polished report even when the source data is incomplete.
The right choice is not always the one that produces the smallest gain today. Holding period, available losses, future income, state tax, and the quality of your records can all change the answer.
FIFO, HIFO, and specific identification compared
| Approach | What it does | What it requires | Main risk |
|---|---|---|---|
| FIFO | Uses the earliest acquired units in that wallet or account first. | Complete acquisition and transfer records. | Old low-basis lots may create a larger gain. |
| HIFO | Selects the highest-basis available units first. | Adequate specific identification made on time. | Software may label a report HIFO without proving the required identification. |
| Specific identification | Selects particular units based on supported identifiers. | Timely instructions plus records for the selected units. | A later reconstruction may not satisfy the identification rule. |
FIFO is a fallback, not automatically a mistake
FIFO can produce long-term gains when the oldest lots have been held for more than one year. It may also produce a loss when the earliest lots have a high basis. You need the actual lot history before deciding whether FIFO helps or hurts.
HIFO is selection logic
HIFO is shorthand for selecting the highest-basis lots. The IRS rules focus on whether the disposed units were adequately identified, not on a software dropdown named HIFO.
That distinction matters. Choosing HIFO after the year ends does not automatically create a valid contemporaneous identification.
What specific identification requires after 2025
For units held in a hosted wallet or exchange account, the current IRS digital-asset FAQs say you must identify the units to the broker no later than the date and time of the sale. The identification must use the identifiers the broker designates, and you must retain adequate records.
If you do not adequately identify the units, FIFO applies within that hosted wallet or account. Standing instructions can work for later sales, but they must already be in place with the broker and use the broker’s accepted identifiers.
The temporary transition relief in IRS Notice 2025-7 applied to qualifying 2025 broker transactions. It should not be treated as a permanent rule for sales in 2026.
For an unhosted wallet, adequate records still matter. If you do not make a supported identification, the IRS FAQ default is FIFO within that wallet, regardless of when units were transferred into it.
Wallet-by-wallet and account-by-account basis
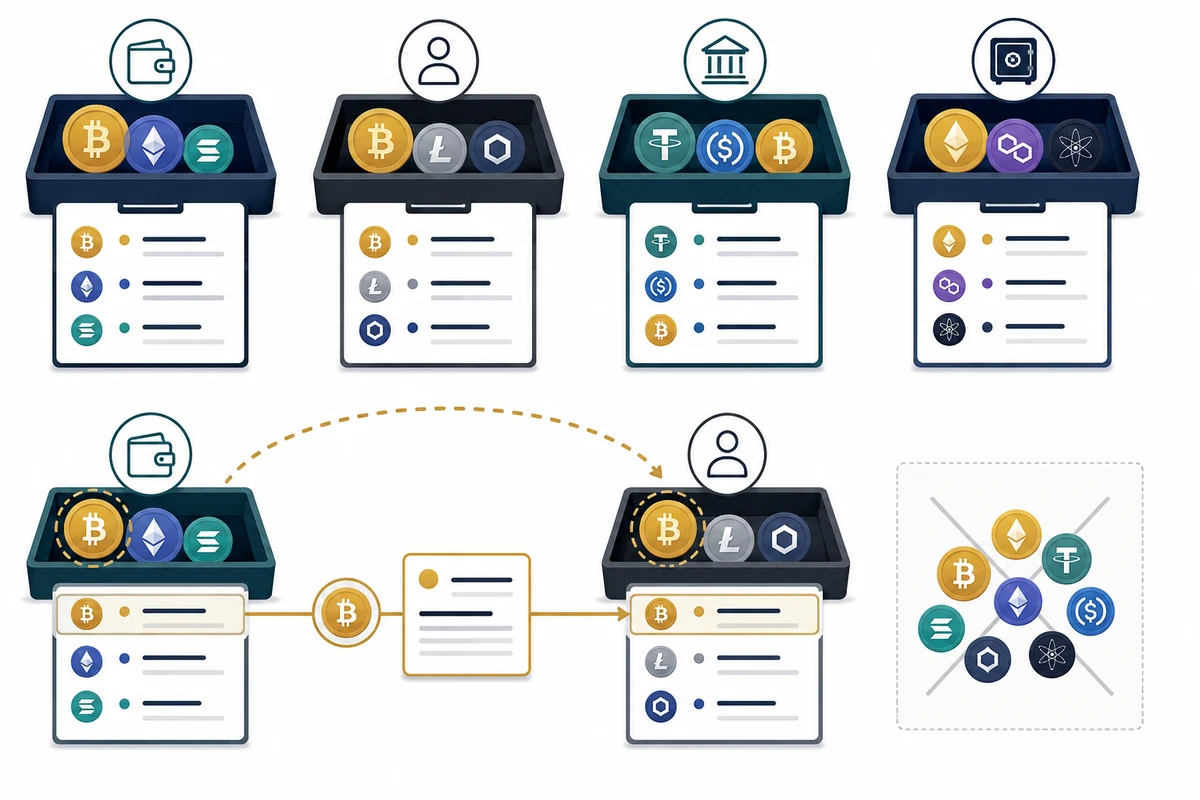
The universal or multi-wallet approach ended for digital assets held on January 1, 2025. Basis is now tracked separately for each wallet or account. Rev. Proc. 2024-28 provided a safe harbor for allocating previously unattached basis into those wallet-level pools if its conditions were met.
A broker may report gross proceeds on Form 1099-DA without reporting basis for every transaction. Proceeds alone do not establish your gain. Your ledger still needs acquisition dates, basis, transfers, fees, and the units disposed of.
Self-transfers, network fees, and lot continuity
Moving your own asset between wallets you control is generally not a sale. The original basis and holding period travel with the asset, so the transfer record must connect the sending lot to the receiving wallet.
A network fee paid in cryptocurrency can be a separate disposition of the fee units. Do not delete fee transactions just because the principal transfer is not taxable.
If ownership of the destination wallet is unknown, treat it as an unresolved item. A blockchain address shows movement, but it does not prove who controlled the destination.
A defensible lot-selection workflow
- Reconcile the inventory first. Confirm every acquisition, disposal, income item, fee, and self-transfer.
- Separate wallets and accounts. Do not optimize one universal pool.
- Compare after-tax outcomes. Review basis and holding period, not only the largest available basis.
- Make the identification on time. Follow the broker’s accepted procedure before or at the sale.
- Keep evidence. Save broker confirmations, transaction IDs, acquisition records, and the calculation used.
- Review the final tax forms. Reconcile Form 1099-DA information to your transaction ledger and Form 8949 schedule.
Tax software can help with the calculations, but it cannot repair missing ownership evidence or create a timely instruction after the fact. Before relying on a report, test a few disposals all the way back to their source records.
Koinly
Useful for consolidating exchange, wallet, and blockchain activity before reviewing lot assignments.
Review KoinlyCoinLedger
Another reporting option worth testing against your actual wallet and exchange records.
Review CoinLedgerRelated Bugaboo guides
- Short-term and long-term crypto capital gains
- When staking rewards become taxable income
- DeFi swaps, liquidity pools, and yield-farming records
- Crypto tax reconciliation services
Frequently asked questions
Is HIFO an IRS-approved crypto cost-basis method?
HIFO is best understood as a specific-identification strategy. It is supportable only when the selected units are adequately identified and documented under the applicable rules.
What happens if I cannot identify the crypto units sold?
FIFO generally applies within the wallet or account involved. Complete transfer records are still needed to establish the basis and holding period of those units.
Can I choose HIFO after the sale?
Generally, no. Hosted-wallet identification must be communicated to the broker no later than the sale’s date and time under the current IRS FAQ procedure.
Can I combine all wallets into one cost-basis pool?
No. Beginning in 2025, digital-asset basis is tracked wallet by wallet and account by account rather than through a universal pool.
Does Form 1099-DA give me complete cost basis?
Not always. Reconcile the form to your ledger because reported proceeds may not include basis for every covered and noncovered transaction.
Sources reviewed
Fact-checked September 8, 2026 against IRS digital-asset transaction FAQs, Rev. Proc. 2024-28, Notice 2025-7, and the IRS digital-assets filing hub.
Find the record problems before choosing a method
The Diagnostic identifies missing history, unsupported transfers, and lot-selection issues, then scopes the separate reconstruction work needed. It does not perform the cleanup itself.
Request the Crypto Tax Diagnostic